Gold and copper prices are rising fast. That’s a fact that’s impossible to ignore.
What many people are missing is that the opportunity to gain early exposure to companies exploring for these metals in Tier-1 jurisdictions may not last forever.
That’s where one little-known Canadian explorer comes into play. It has a small market cap and low share price alongside a strong treasury and major-company-funded drilling underway now in two premier Australian mineral belts.
Successful drilling could bring greater market attention to the copper-gold potential the company is targeting across its portfolio.
Access our brand-new FREE report to get the full story.
Inside, you’ll learn the company’s name and ticker symbol, explore its Australian project portfolio, and get the latest on drilling now underway.
Access the report by clicking here and learn just why this overlooked copper-gold explorer is well-positioned for significant upside.
On Running Wants Investors to Buy Its Next-Brand Pitch
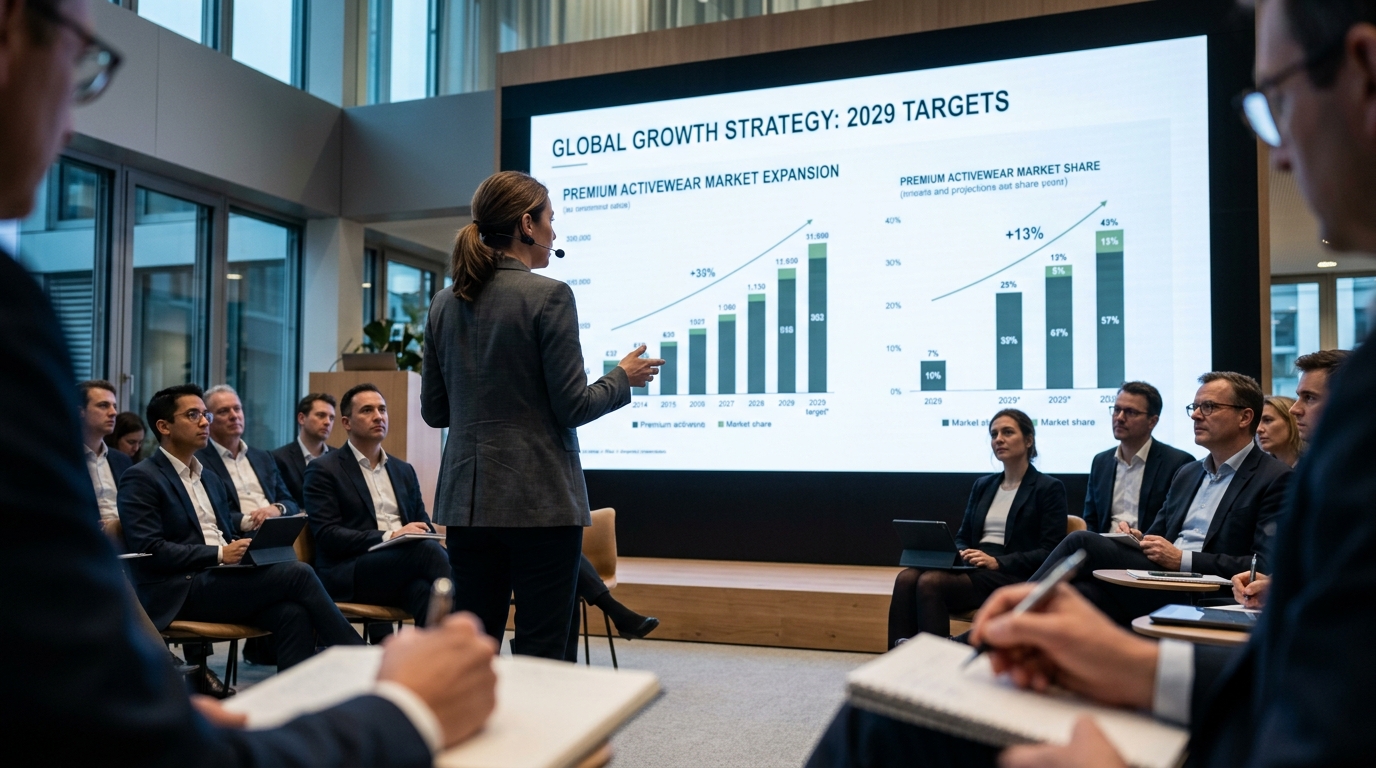
The footwear industry has not produced a genuinely new category-defining franchise since Lululemon proved that premium activewear could grow into something durable. On Running is making its case today that it is next in line. The Swiss brand’s investor day at On Labs in Zurich, which began at 8 a.m. Eastern time this morning, is the most important capital markets event in premium footwear this year, and it lands at a genuinely unusual moment: the incumbent is struggling while the challenger has to prove it is something more than a beneficiary of Nike’s slump.
For the 2026 to 2029 period, On is targeting net sales of at least CHF 5.6 billion by 2029, or roughly $6 to $7 billion at recent exchange rates, on the back of high-teens constant currency annual growth. The company also aims to sustain a gross profit margin of at least 65% and reach an adjusted EBITDA margin of at least 22% by 2029. Alongside those numbers, On’s board authorized its inaugural share repurchase of up to $1 billion of Class A ordinary shares through the end of 2029.
Those are serious numbers. On says it is on track to significantly exceed the 2026 financial targets it introduced at its 2023 investor day. Full-year 2025 net sales reached CHF 3.014 billion, up 30% on a reported basis, with a 62.8% gross margin. A company that consistently beats its own targets earns the right to set ambitious new ones.
The harder question is not whether On can grow. It is whether the growth compounds into something structurally defensible. On’s key growth pillars through 2029 span run, sneaker, and apparel, with planned expansion into football and golf. Category extension is where premium brands either prove their staying power or dilute what made them special. Hoka stayed tightly focused on performance running and grew to $2.587 billion in fiscal 2026 revenue, up nearly 16% year-on-year. On is swinging for something bigger and broader, which raises the execution risk considerably.
The backdrop is not irrelevant. Nike’s shares recently traded in the high $30s and, in August, closed at their lowest level in roughly 12 years. From a November 2021 record close of $177.51, the drawdown has been about 78%. Nike’s running and wholesale channels are improving, but Direct, digital, and China remain weak. Reuters reported in July that Nike has suffered eight consecutive quarters of falling sales in China. On has benefited from that vacuum. The question a disciplined investor has to ask is how much of On’s momentum reflects genuine brand building versus temporary displacement from a stumbling giant.
About 93% of On’s revenue still comes from shoes. In its 2025 annual report, On said it sourced about 90% of its shoes from Vietnam. That concentration is a real risk, and no amount of aspirational framing at an investor day makes it disappear. For 2026, On has reiterated a full-year outlook that calls for constant currency net sales growth in the low-20% range, with the direct-to-consumer channel expected to outperform wholesale in the second half as it manages inventory discipline.
What makes On genuinely interesting is the margin profile. A 65% gross margin target at scale would be exceptional for a footwear company. The relevant comparison with Nike is not scale but margin and momentum, and on both counts On currently leads. If On can extend that margin advantage into apparel and new categories while maintaining pricing discipline, the case for a lasting consumer franchise becomes substantially more credible.
Nike reports October 1, 2026. That report will tell investors whether the incumbent is stabilizing or still sliding. On’s investor day today forces the market to answer a related but separate question: can a brand born in the Swiss Alps at premium price points earn the loyalty, distribution breadth, and category span of a generational franchise? The targets are ambitious. The track record so far is real. What remains unproven is whether On’s competitive advantage deepens as it gets bigger, or whether it is an advantage that only works at its current scale.