October 15, 2026
Bonus Content: Nvidia Lost Half Its China Market. Does CUDA Go With It?
The Silver Institute says expanding data centers and AI-related technologies are driving silver consumption across industrial uses.
That’s because behind AI’s digital world is a very physical one: chips, servers, electrical systems and massive infrastructure.
Now add a 6th consecutive year of more silver consumption than production and you have a significant deficit.
For investors, that puts a new spotlight on where future silver may come from.
Nvidia Lost Half Its China Market. Does CUDA Go With It?
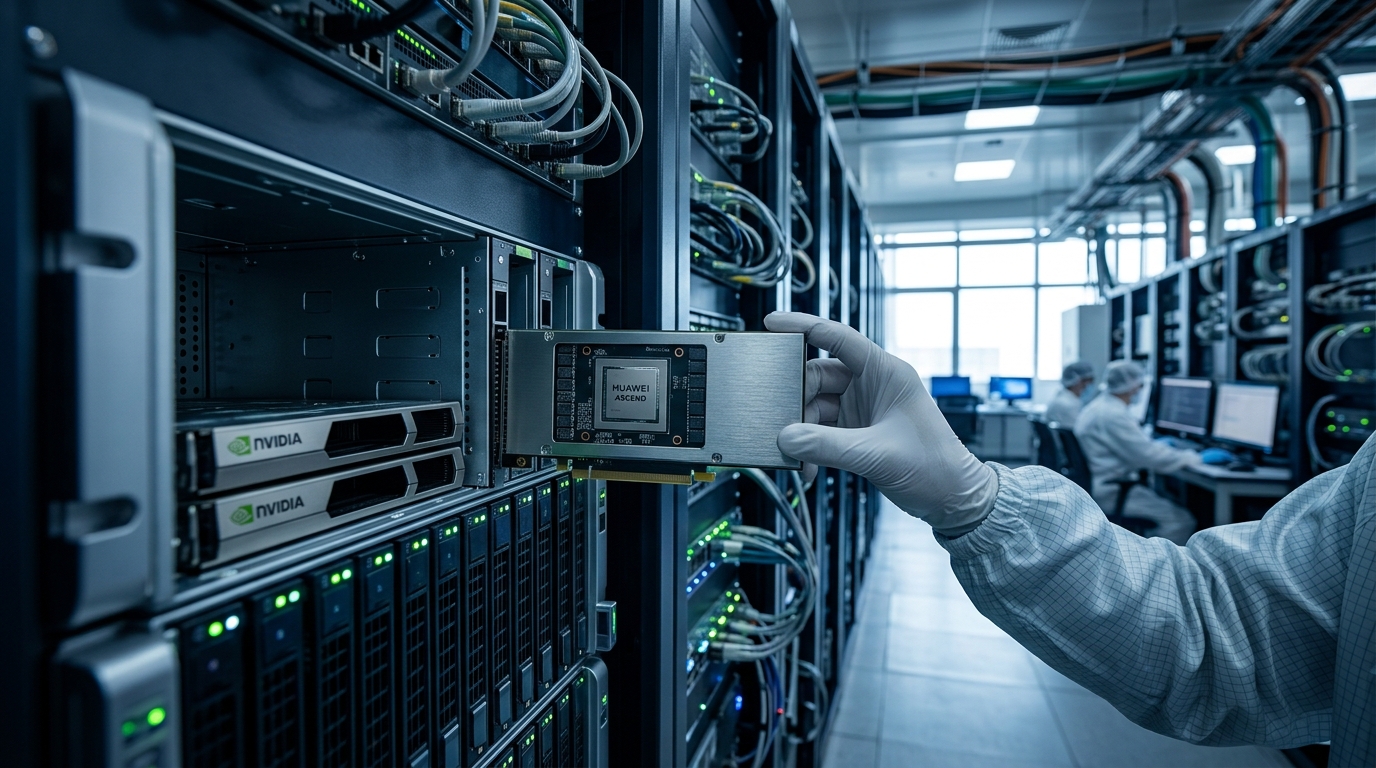
The numbers IDC handed Reuters on October 13 are not ambiguous. Nvidia’s share of China’s market for data-centre AI chips fell to 34% in the first half of 2026 as U.S. export restrictions limited supplies and domestic competitors, led by Huawei, gained ground. A year earlier, the gap between the two companies stood at 31 percentage points. It now stands at six.
Nvidia shipped 678,000 AI accelerators in China between January and June, down 44% from a year earlier. Huawei shipped 572,000, up from more than 300,000 a year earlier, capturing 28% of the overall market. Jensen Huang has been saying this would happen for months. He has repeatedly criticised Washington’s export curbs, arguing the policy forced a U.S. company to cede China’s $50 billion AI chip market to Huawei. This week, the data confirmed it.
Most coverage frames this as a geopolitical story. It is also an investment thesis stress test. Nvidia’s bull case has never rested entirely on silicon. It rests on CUDA, the software ecosystem the company has been compounding since 2006. What competitors cannot easily build is two decades of software that the entire AI industry has been written on top of. For nearly two decades, CUDA has been the default platform for general-purpose GPU computing. Universities teach it, and researchers publish CUDA-based code. That accumulated weight is what makes Nvidia’s position resilient in most markets. The question China now poses is whether software lock-in survives when the hardware it locks you into becomes legally unavailable.
The early evidence is that it does not survive cleanly. Export restrictions are doing more than temporarily reducing Nvidia sales. They are giving Chinese customers stronger incentives to build around local hardware ecosystems. Huawei is not passive about this opportunity. In August 2025, it announced the open-sourcing of the CANN toolkit and has been recruiting Chinese AI labs, universities, and research institutions to contribute to an open Ascend developer community. Huawei executives later said external CANN developers now comprise 61% of all CANN developers, outnumbering internal developers for the first time, with over 5,200 monthly active developers.
That is not CUDA. But it is no longer nothing. Claims that roughly 80% of standard PyTorch inference workloads can run on Ascend with minor adjustments through CANN are difficult to verify as a general figure, and likely vary widely by model, operator coverage, and deployment stack. What is clear is that CANN and related projects aim to support PyTorch workflows, and Huawei has been pushing compatibility and migration tooling. Huawei also points to collaboration with DeepSeek and other ecosystem partners, which can lower the friction for developers familiar with Nvidia stacks to try Ascend hardware.
The harder structural risk is what IDC flagged almost in passing. Competition is shifting from the performance of a single chip to system-level capabilities, including how well chips work in a larger computing cluster. Reuters also reported, citing IDC, that shipments of non-GPU AI chips surged nearly 80%, surpassing GPUs in volume for the first time. That matters because CUDA’s grip is strongest on GPU-centric workloads. As the Chinese market reorients around non-GPU accelerators and domestic software stacks, the switching costs Nvidia depends on erode at the source.
None of this makes Nvidia a broken business. Its dominance outside China remains essentially unchallenged, and IDC expects total accelerator shipments in China to grow 19% this year even as GPU shipments fall 9%, meaning the market is expanding without Nvidia. The sharper concern for long-term investors is whether a generation of Chinese engineers building on Ascend and CANN today becomes a generation that never returns to CUDA, and whether that eventually exports a competing software standard to markets where Nvidia currently faces no such pressure.
China is now less a revenue line for Nvidia than a controlled experiment in what happens when customers are forced off CUDA entirely. The results, so far, suggest that the moat holds better in places where the hardware is still available.