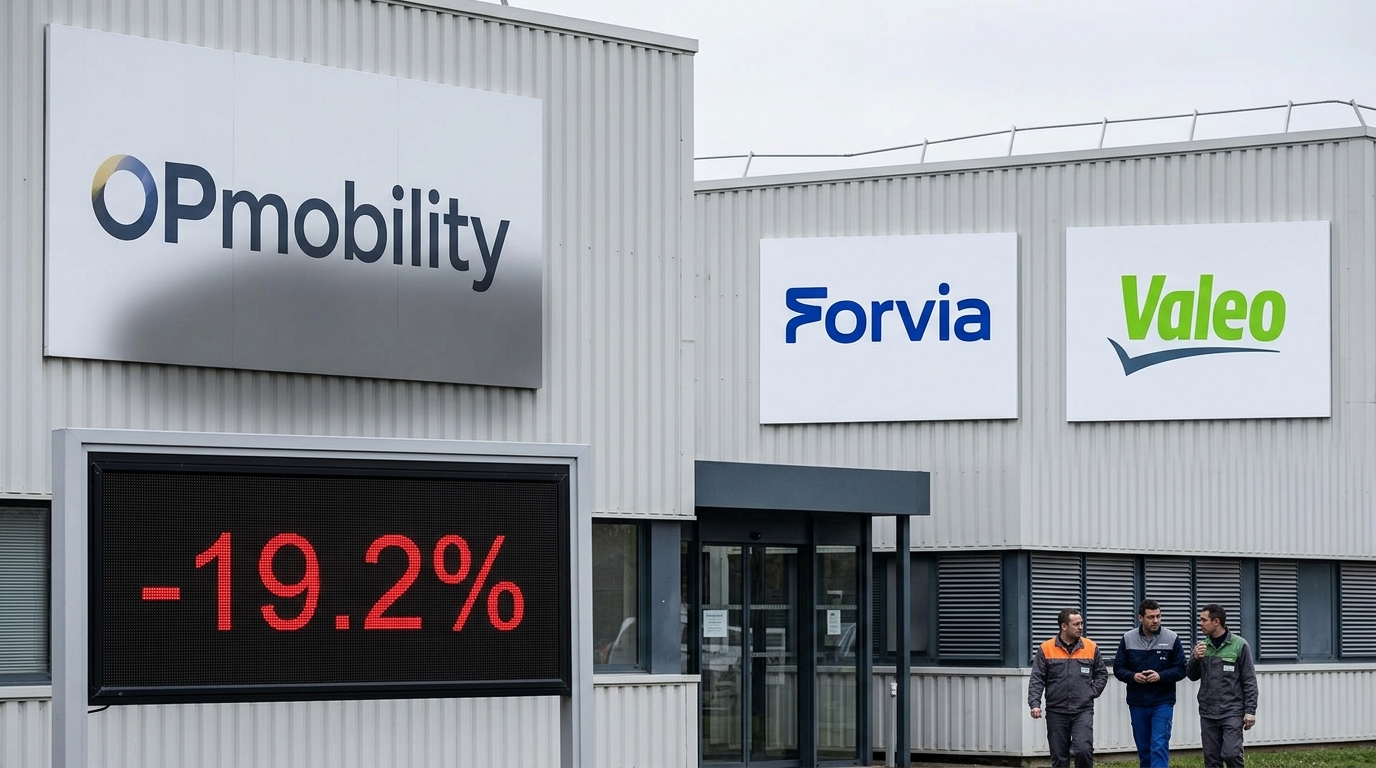
OPmobility stock plunged 19.2% to trade at €10.05 after the company released a disappointing update after the Paris market close on October 7, cutting its 2026 financial targets and announcing a sweeping European restructuring program that caught investors off guard.
Market Snapshot
Management now targets a 2026 operating margin of between €430 million and €450 million, down from the €490 million delivered in 2025. Free cash flow is now expected to exceed only €220 million, compared to €297 million generated last year. Prior guidance had called for improvement, not a step back. That gap between expectation and reality is what drove the gap down at the open.
Sector peers Forvia and Valeo also declined on the day, reflecting broad stress across the European auto supplier space as the market digests the worsening industry backdrop.
Stocks in Focus
OPmobility (OPM.PA): The company will cut around 460 jobs in Germany and 310 in France to address excess manufacturing capacity, resulting in the closure of two R&D facilities in France and the shutdown of the Sterbfritz exterior parts plant in Germany. OPmobility expects €120 million to €130 million of restructuring costs in 2026 as it closes sites, adjusts capacity, and streamlines R&D. The restructuring bill alone eats well over half of the €220 million free cash flow target, making execution the key variable for the rest of the year.
Deutsche Bank responded to the announcement by lowering its price target on the stock to €11 from €14, maintaining a Hold rating, reinforcing the negative sentiment. Watch whether any analyst flips to Sell: that would likely extend the selling into Friday.
Forvia and Valeo: Neither company has issued fresh guidance, but both trade on the same European production volume assumptions OPmobility just downgraded. If institutional money concludes the guidance reset at OPmobility is sector-wide rather than company-specific, Forvia and Valeo absorb that reset next. BMW and Stellantis (STLA) are also worth monitoring as OEM proxies for European order flow.
Sector Watch
The company attributed the revision to a worse-than-anticipated decline in global auto production forecasts, weakening customer activity across Europe, ongoing geopolitical tensions in the Middle East driving raw material price volatility, and project cancellations in the hydrogen mobility sector in both the United States and Europe.
That list covers three separate demand headwinds at once: cyclical volume weakness, structural combustion phase-out uncertainty, and the collapse of hydrogen as a near-term revenue story. European auto suppliers have been carrying all three into 2026, and today’s move reflects the market finally pricing that combination properly.
Risk Radar
- Contagion to Forvia and Valeo. Both are exposed to the same European OEM customer base. A read-across to their own guidance becomes the central risk heading into their next updates.
- Restructuring execution. OPmobility is projecting more than €220 million of free cash flow in 2026 while also flagging €120 million to €130 million of restructuring costs in the same year. The one-off bill is well over half of the annual cash number the company is aiming for.
- Hydrogen project cancellations spreading. Customers have cut development as the EU’s 2035 combustion engine phase-out nears and hydrogen projects are cancelled in the US and Europe. Any further cancellations widen the revenue hole at suppliers banking on that business.
The Cheat Sheet
- Top Market Theme: European auto suppliers are resetting expectations as OEM customers pull back faster than guidance assumed.
- Stock to Watch: OPmobility (OPM.PA). Down nearly 20%, but the free cash flow math is tight enough that any execution miss reopens the downside.
- Sector to Watch: European auto parts. Forvia and Valeo are the names most exposed to the same conditions that forced today’s guidance cut.
- Biggest Risk: A read-across forces Forvia or Valeo to pre-announce their own guidance revision before scheduled results.
- Biggest Opportunity: If today’s move overshot and the restructuring delivers, OPmobility at €10 could be cheap. Deutsche Bank’s new €11 target implies limited upside at current levels, so wait for confirmation the cash targets hold.
- One Thing to Remember: OPmobility’s problem is not unique to OPmobility. Any European supplier heavily weighted toward German or French OEM volumes is carrying the same exposure.