Watch the airlines Monday. The fuel shock that has been building since early August just landed a concrete number: American Airlines says a roughly $1-per-gallon increase in jet fuel over the past four weeks would add approximately $1 billion to its fourth-quarter operating costs. American, United and Southwest have all decided the answer is fewer flights, not a bigger fuel bill.
Market Snapshot
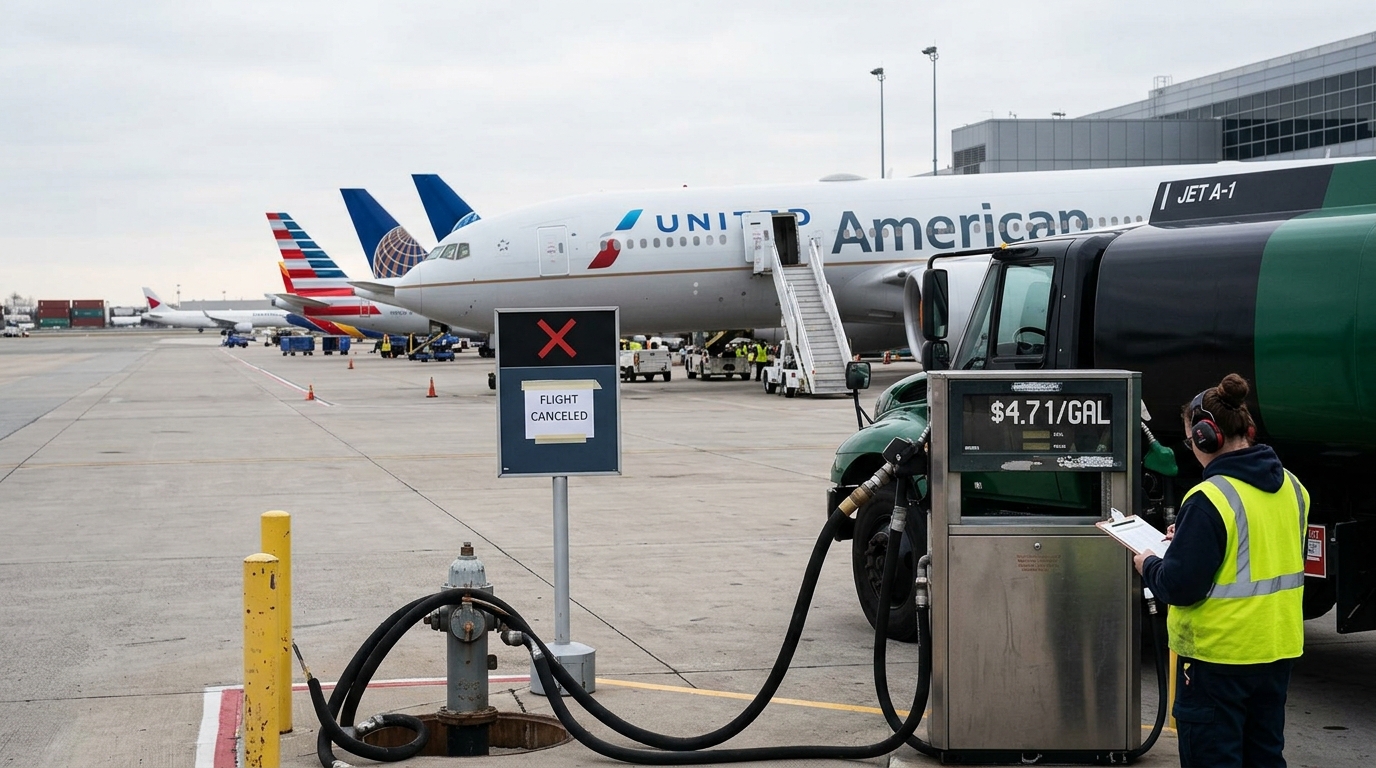
Crude futures have been swinging around the low-$100s after oil surged sharply since early August, and fuel-sensitive stocks have already been moving lower. Diesel is at record highs on AAA’s national average, above $6 per gallon this week. Jet fuel is moving with the same distillate market: jet fuel has climbed to about $4.71 per gallon on the U.S. Gulf Coast, more than double the cost a year ago and near a multi-year high. The fuel shock is tied to disrupted shipping through the Strait of Hormuz, Russia’s diesel export ban, and tight global refining capacity.
Stocks in Focus
- AAL: CFO Devon May told a Morgan Stanley investor conference that fuel prices have risen by roughly $1 per gallon in the past four weeks, which would add about $1 billion in additional fuel costs over a full quarter. American also said it will keep adjusting capacity late in the fourth quarter of 2026 as fuel volatility persists.
- UAL: United said it would drop some flights it had planned to operate in December, with further cuts possible into early 2027 if fuel prices stay high. CFO Michael Leskinen told the conference, “We are not flying to maximize market share. We’re flying to maximize profitability and free cash generation.”
- LUV: Southwest initially planned capacity growth of about 2% to 3% for 2026 but said that expectation has been cut by about half due to higher fuel costs. CFO Tom Doxey said trimming capacity was the “natural response” if fuel stayed higher for longer.
- DAL: Delta looks relatively more protected compared to American and United in the current environment. That distinction matters when positioning within the group.
- CCL / RCL: For cruise operators, Carnival faces the clearest risk because it buys fuel largely at spot-market prices rather than relying on hedges. Royal Caribbean has said its full-year fuel expense is projected at approximately $1.35 billion, with about 59% of remaining 2026 fuel consumption hedged at rates below current market levels, giving it a structural buffer Carnival lacks.
Sector Watch
Demand is not the problem. All three carriers have cited strong demand despite high prices, which has so far let them stay ahead of rising costs. But the most recent hike has forced them to slash capacity on routes with thinner margins. That means the pain is concentrated in operating costs, not revenue, which narrows the playbook: carriers that hedge better or run leaner route maps have the clearest path through Q4.
Jet fuel costs have also squeezed airlines across the Atlantic. Ryanair cut its full-year passenger forecast for the year ending March 2027 from 216 million to 214 million as it trimmed winter flying to reduce exposure to expensive unhedged fuel. The supply squeeze is global, not regional.
Risk Radar
Goldman Sachs has forecast U.S. diesel refining margins at $63 per barrel in 2027, reinforcing the risk that distillate markets stay structurally tight. That is the core risk for anyone long the airlines into Q4 earnings.
Corporate travel departments should anticipate sustained upward pressure on airfares as airlines continue to pass fuel cost increases onto the market. Higher fares on fewer seats could eventually dampen the demand strength executives are still citing.
The Cheat Sheet
- Top Theme: Fuel cost, not demand, is reshaping Q4 airline capacity across all three major U.S. carriers simultaneously.
- Stock to Watch: AAL. The roughly $1 billion Q4 fuel overrun is specific and quantified. It sets the floor for what Q4 earnings expectations need to absorb.
- Sector to Watch: Airlines and cruise. Both move directly with oil, and expensive distillates put every unhedged operator on the wrong side of the cost line.
- Biggest Risk: No Hormuz normalization in sight. Higher-for-longer refining-margin forecasts point to elevated jet fuel well past year-end.
- Biggest Opportunity: DAL and RCL relative to AAL and CCL. Hedging and route quality create a spread trade within the same macro shock.
- One Thing to Remember: When three carriers flag capacity trims at the same investor conference, the market may still be catching up to the combined Q4 earnings revisions. Watch for analyst downgrades this week.