The calm corner of the market is no longer calm. Global credit markets have started to show signs of caution, with spreads on global corporate bonds blowing out roughly five basis points in the week ended October 2, the most since March, leaving risk premiums at their widest in six months. The question every credit committee is arguing this week is whether that move is simple indigestion from a record pipeline, or the first honest reset of a cycle that equity markets have yet to price.
The Scale of the Problem
The supply shock is real and measurable. JPMorgan projects that global bond issuance in the technology, media, and telecommunications sector will reach a record $540 billion in 2026, driven by accelerating AI infrastructure investment, with bond sales from Amazon, Alphabet, Meta, and Oracle rising sharply year-over-year in the first half. That flood is now competing for the same wallets at exactly the wrong moment: the 30-year Treasury yield rose for a sixth straight day in late September, crossing above 5.61% to touch a level last seen in 2002, with the move tied to inflation worries and heavy corporate-debt supply.
The AI borrowing is only one half of the supply problem. Record bond sales recently from Paramount Skydance to SoftBank have added to the surge in corporate debt supply now giving money managers pause. Paramount Skydance raised roughly $52 billion across bonds and loans to help fund its Warner Bros. Discovery buyout. Its junk tranches were among the weakest in initial trading, while SoftBank had to pay record yields, including 9.75% on a 7.5-year bond, to push through an approximately $11.1 billion multi-currency deal.
The Bull Case: Indigestion, Not Insolvency
BlackRock’s fixed income team has argued that the widening in AI-related spreads reflects straightforward supply-and-demand dynamics rather than growing concerns about credit quality, and that the trade-off remains attractive for both issuers and investors. The fundamentals backstop that view, at least for the largest names. Microsoft, Alphabet, Amazon, and Meta have ample leverage headroom and could add hundreds of billions more debt in aggregate before there is any pressure on their ratings. Paramount Skydance itself attracted more than $109 billion of investor orders for its investment-grade bond offering, representing approximately 3.6 times the amount expected to be sold. Demand exists. The price of that demand is the dispute.
The Bear Case: Reset, Not Recovery
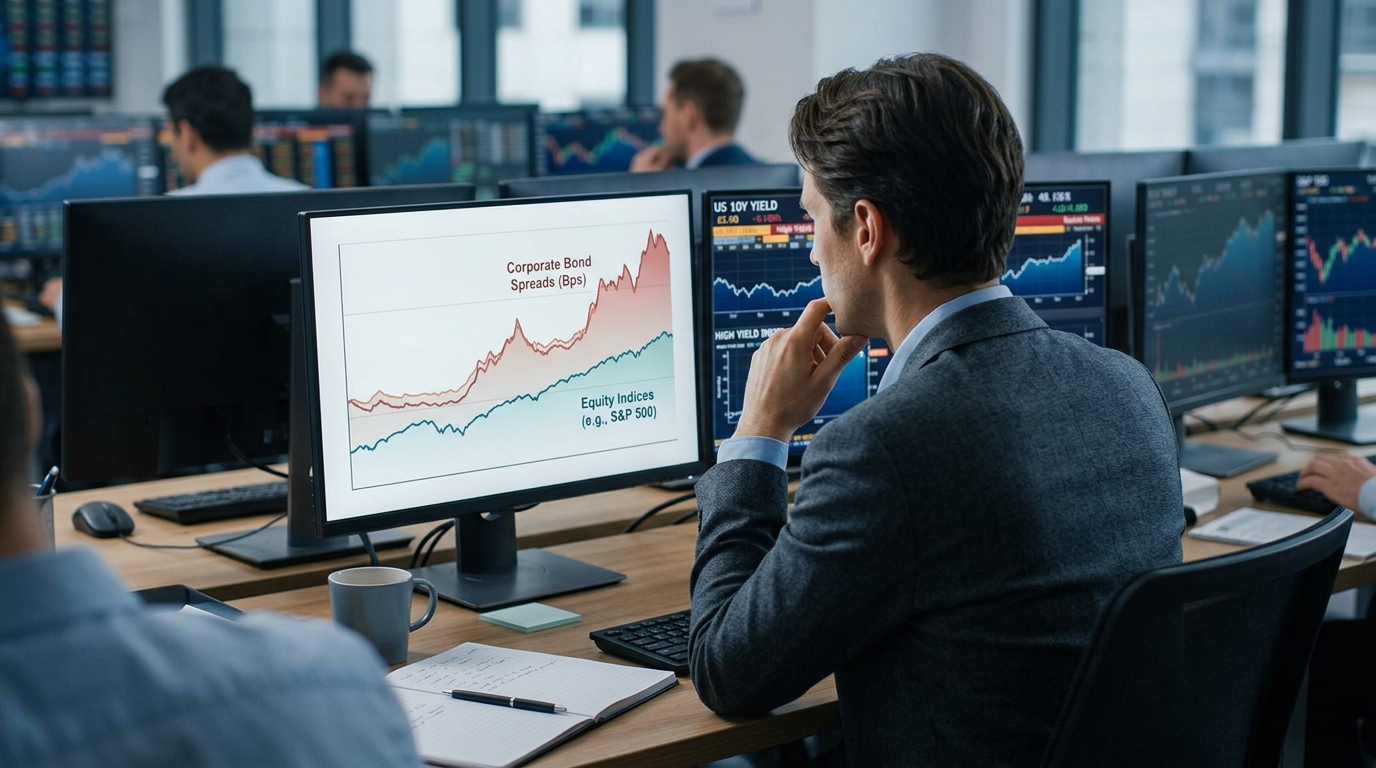
The bearish read starts with a detail the orderbook headlines obscure. The average extra yield on U.S. high-yield corporate bonds over Treasuries widened 12 basis points to 294 basis points, the highest since April. CCC-rated bond spreads closed at 968 basis points, the highest since November 2023. On the investment-grade side, the average spread on U.S. high-grade corporate bonds widened 3 basis points to 80 basis points, nearing Goldman Sachs’s third-quarter forecast of 85 basis points.
The credit default swap market is more pointed. Apollo Global Management chief economist Torsten Slok noted that spreads are widening out for hyperscalers and that Oracle’s CDS is around the same level it was at in 2008. S&P Global downgraded Oracle to BBB-, just one notch above junk, in July 2026, while Oracle’s 5-year CDS rates traded at multi-year highs. That is not indigestion language. High-yield OAS widened sharply to around 294 basis points even as the S&P 500 rose over the same window, a divergence often attributed to record primary supply rather than deteriorating fundamentals. The divergence between credit and equity is precisely what makes the current moment alarming for institutional investors who watch both.
What Investors Are Missing
The debate is framed as supply versus quality, but the more important question is absorption capacity. Apollo’s midyear outlook put it directly: public markets are being stretched by record financing needs, spreads leave little room for error, and traditional notions of diversification are being tested. Gross issuance across corporate debt and loan markets reached $1.8 trillion in the first half and could approach $3.2 trillion for full-year 2026, well above the previous annual record of $2.8 trillion set in 2021.
The hidden risk is not Oracle or Paramount individually. It is that every successive jumbo deal arrives into a market already digesting the last one. Each successive jumbo deal has pressured spreads wider before they eventually stabilize and experience modest rallies, and this supply dynamic has been a primary driver of hyperscaler underperformance in 2026. If the 30-year yield stays above 5.60% and high-yield CCC spreads hold near 1,000 basis points, equity multiples built on the assumption of cheap corporate capital will need to reckon with a borrowing world that looks nothing like 2024.
Stocks to Watch
- Oracle (ORCL): Oracle’s 5-year credit default swap has become a widely watched proxy for AI debt fears, and it has been trading near multi-year highs. A further ratings cut to junk would force index-fund selling of its bonds, compounding the pressure.
- Meta (META): Credit spreads on Meta’s bonds have been widening alongside those of Alphabet and Amazon, signaling investor demands for higher returns across the sector. Meta’s equity has held up; its bond market has not.
- Broadcom (AVGO): Broadcom’s CDS has widened alongside other large AI-linked issuers as the market treats the AI buildout as a shared financing problem.
- Paramount Skydance (PARA): The combined company is expected to carry roughly $80 billion in debt against roughly $3.8 billion EBITDA, putting leverage at about 7.6 times through 2027. That is where credit stress becomes an equity story.
- JPMorgan (JPM) and BlackRock (BLK): Both are central to syndicating the deals flooding the market. Wider concessions on primary issuance compress underwriting economics but also signal where the real clearing price for risk now sits. Watch their credit commentary in October earnings for the clearest institutional read on whether this is a pause or a turn.