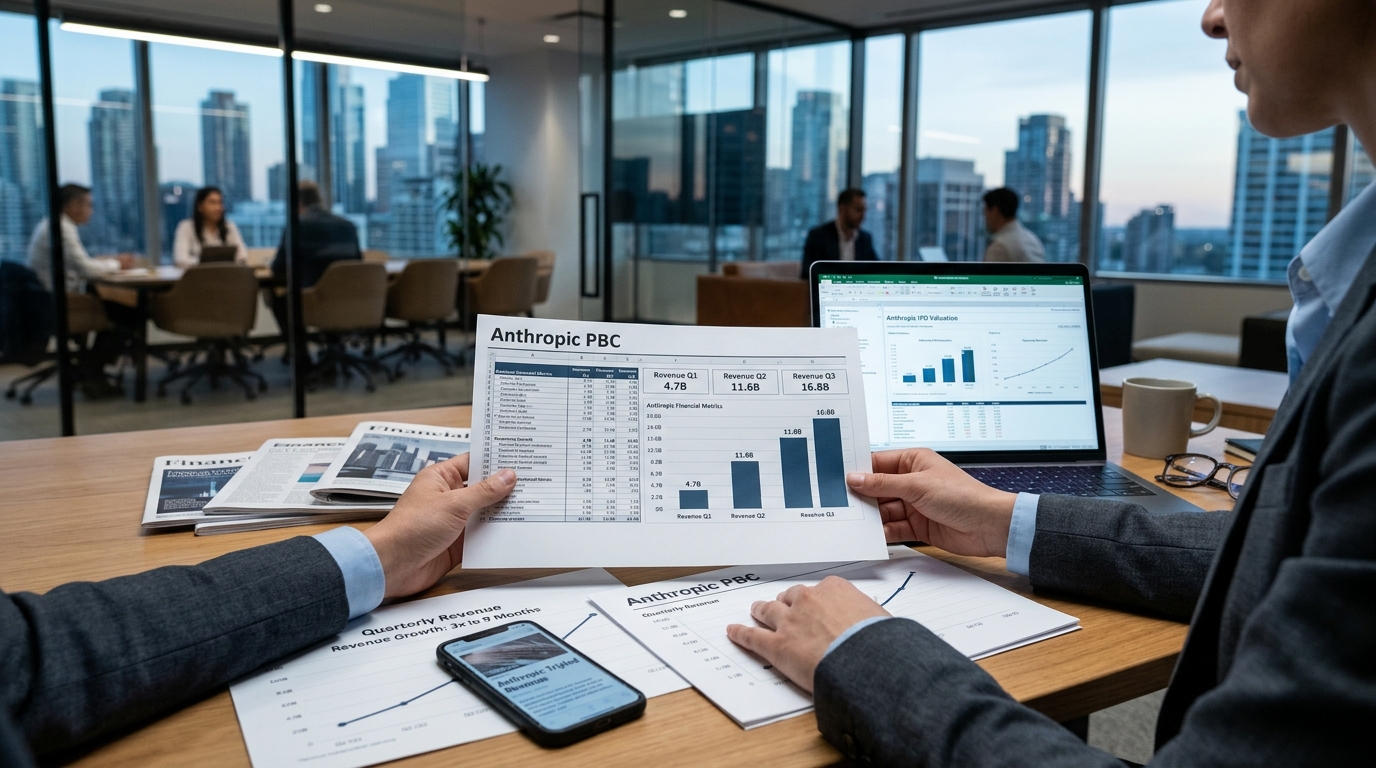
There are very few businesses in history that have grown as fast as Anthropic has in 2026. Revenue rose from $4.7 billion in the first quarter to $11.6 billion in the second, then to $16.8 billion in the third. That is not a typo, and it is not annualized. Those are quarterly figures, each one larger than the last, covering a nine-month span. A single quarter’s revenue now exceeds all of Anthropic’s first-half output combined.
The Claude maker disclosed the Q3 figure at a closed-door investor meeting in San Francisco on October 14. The briefing also disclosed that Anthropic was profitable on an adjusted basis in the quarter, but the company has not publicly provided enough detail to confirm an 85% adjusted gross margin. Reports from the meeting also said the company was cash-flow positive and generated $1.70 in revenue for every dollar spent on computing power. For a company that spent most of its life burning capital with no clear path to break-even, the adjusted numbers look almost implausible.
Almost. The operating reality underneath is more complicated, and long-term investors should read it carefully before the expected November listing.
The Cost Structure That Matters
Anthropic’s draft IPO prospectus shows an $80.7 billion net loss in H1 2026 on $16.3 billion of revenue, including a $72 billion non-cash charge tied to convertible notes and other financing instruments. Strip that out, and the company still ran an operating loss. On a full-year 2025 basis, revenue grew 12-fold to nearly $4.6 billion, but the company spent $7.33 billion on computing and infrastructure, triple the prior year, accounting for more than half of its $12.65 billion in total operating expenses.
In just the first half of 2026, Anthropic spent $9 billion on cloud services, chips, and other computing costs, up sharply from $2.3 billion in the same period a year earlier. Revenue is outpacing the compute bill, but the compute bill is also growing at speed. In its IPO paperwork, Anthropic said it expects to spend at least $518 billion over a decade building AI infrastructure with six partners. That is the cost of staying competitive at the frontier, and it does not go away.
The Competitive Frame
Anthropic is not racing against a slow rival. OpenAI has been widely reported at roughly $40 billion in annualized revenue around mid-2026, but reports on its run rate have varied, with later reporting putting it closer to $50 billion. Anthropic’s Q3 pace puts it at roughly $67 billion annualized, closing the gap significantly. OpenAI, for its part, is working to lock in capital before the Anthropic listing lands. It is reportedly close to raising up to $30 billion at a $1.25 trillion pre-money valuation, in a round led by Coatue and UAE investors. Both companies are racing to control the same scarce resources: GPU capacity, enterprise contracts, and the researchers capable of building the next generation of models.
The capital race between the two companies is not just about revenue. OpenAI’s decision to take private capital instead of listing reveals what each company believes it needs to survive the infrastructure buildout.
The Valuation Question
Anthropic’s IPO could value the company at more than $2 trillion, more than double its May 2026 private valuation of $965 billion, pricing in significant expectations for revenue growth, competitive strength, and eventual profitability. Even against the company’s reported 2028 revenue projection of roughly $190 billion to $200 billion, investors would still be paying around 10 times those revenues today.
The adjusted gross margin matters. But a gross margin tells you how efficiently Anthropic monetizes each dollar of compute it buys today. It does not tell you how much compute it needs to buy tomorrow to maintain its position, fund new model development, or defend against a better-capitalized competitor. One analyst estimate in recent coverage modeled a scenario in which Anthropic would need roughly $725 billion in annual revenue by 2036 to support a $2 trillion valuation at a 25% free cash flow margin and a 25x terminal multiple.
The compute cost question is not abstract — it is already reshaping Anthropic’s infrastructure strategy. Anthropic has been signing multi-billion-dollar compute leases in an effort to reduce its dependence on Amazon and Google as cloud landlords.
That is not a reason to dismiss the company. The revenue trajectory is extraordinary by any standard, and while customer mix details vary across reports, Anthropic has been positioned as increasingly enterprise and developer-driven, with Claude Code frequently cited as a growth contributor. The question is whether the cost structure eventually bends toward the margin line, or whether the infrastructure arms race keeps consuming every dollar of incremental revenue the business generates. That is the only question that matters at this price.