Two nuclear deals landed within 24 hours of each other last week, and investors are still treating them as separate stories. They are not.
On September 30, Amazon and Constellation Energy announced a 20-year power purchase agreement tied to continued investment in and expansion of the Calvert Cliffs Clean Energy Center in Maryland, an agreement Constellation said would enable more than $3 billion in Maryland infrastructure investment at the site.
The day after, a quieter arrangement out of Wisconsin made the same argument with even sharper logic for long-term wealth builders.
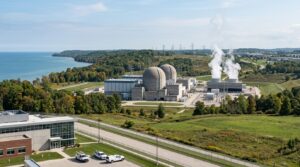
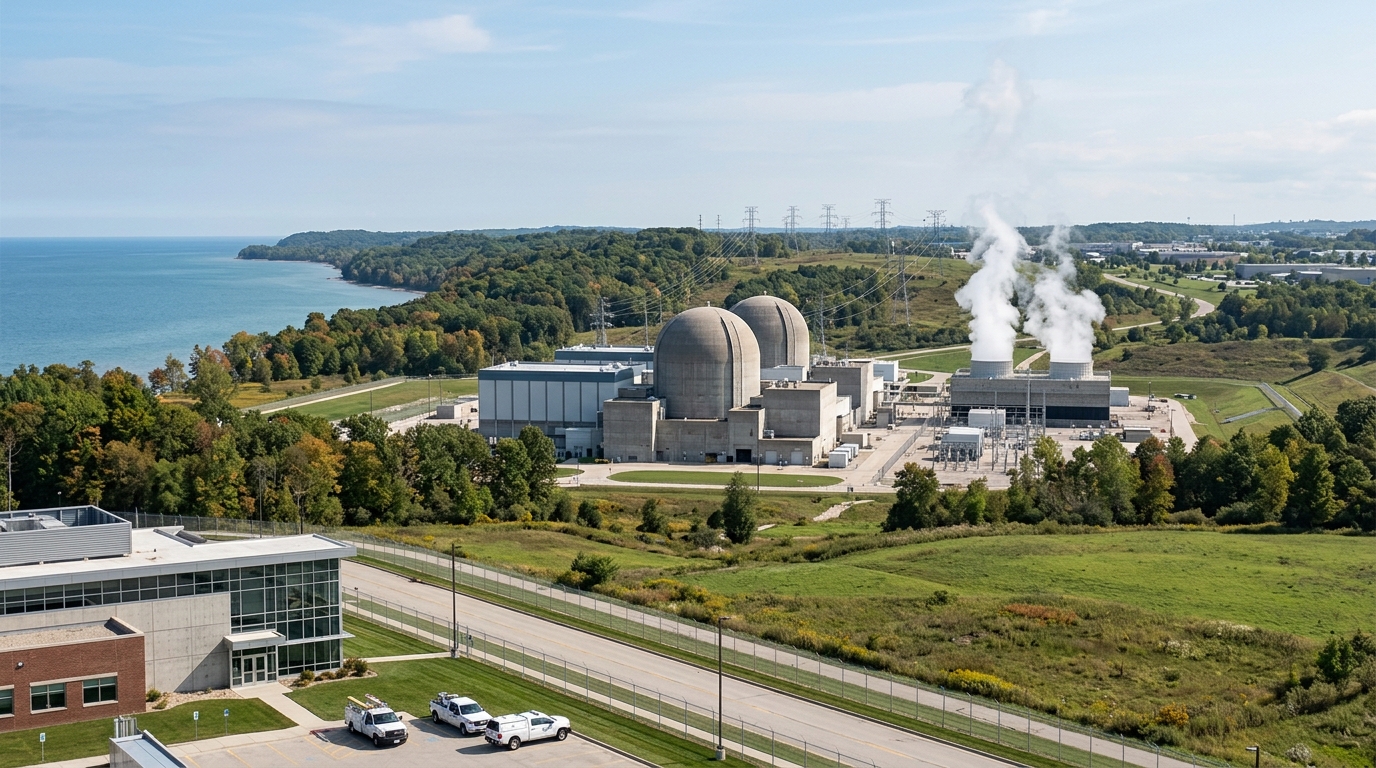
We Energies announced an agreement that would allow Oracle to subscribe to between 10% and 20% of the Point Beach Nuclear Plant’s electricity generation, with that power helping meet the energy needs of Project Lighthouse, the data center campus in Port Washington that Oracle is co-developing with OpenAI. The terms are striking. Oracle says its plan is expected to save utility customers approximately $300 million in fuel costs between 2027 and 2033.
Read that again: a cloud computing giant is voluntarily absorbing hundreds of millions in rising nuclear fuel costs to secure power for its artificial intelligence campus and, in doing so, lowering bills for over a million Wisconsin households. Oracle’s executive vice president of Cloud Infrastructure called it a commitment that “will directly benefit more than 1 million Wisconsin utility customers” by absorbing approximately $300 million in rising energy costs.
This is not philanthropy. It is what happens when electricity becomes as scarce a resource as silicon. We Energies sold Point Beach in 2007 and struck a long-term power purchase agreement tied to the plant’s NRC license terms that run to 2030 for Unit 1 and 2033 for Unit 2. Oracle stepped in to absorb a chunk of that cost precisely because it had no better option for reliable, carbon-free baseload power at scale.
Why WEC Deserves a Different Label
Bulls argue WEC Energy Group is shifting from a bond-like utility to a regulated growth company, powered by data centers and a $37.5 billion capital expenditure plan. The Oracle deal is the most concrete evidence yet that this shift is real rather than projected.
WEC targets a long-term EPS compound annual growth rate of 7% to 8%. It has also forecast weather-normalized electric sales growth of 6% to 8% for 2028 to 2030 and expects to add 3.9 gigawatts of electric demand by 2030, roughly a 45% increase, driven largely by large data center projects. Those are not utility numbers. Those are closer to the growth profiles investors once reserved for mid-cap industrials.
WEC has pointed to decades of consistency against its guidance range and has raised its dividend for 22 consecutive years through 2025. It also raised its quarterly dividend by 6.7% in January 2026. That record of consistency, combined with a demand catalyst that compounds for years, is what separates WEC from peers still waiting for data center contracts to materialize.
Where the Opportunity Sits
The Point Beach deal still requires approval from the Public Service Commission of Wisconsin, so it is not yet locked in. Meanwhile, large purchased-power and fuel costs tied to Point Beach have been a prominent issue in Wisconsin rate discussions. Regulatory friction and balance sheet strain from the capital plan are legitimate risks investors should size for.
But the broader picture is clear. We Energies has disclosed an extended Point Beach power purchase arrangement with NextEra that would run Unit 1 from October 2030 to October 2050 and Unit 2 from March 2033 to March 2053, with the company saying the extension is expected to produce savings for customers compared to current terms. That is a utility locking in carbon-free generation through mid-century, with a hyperscaler co-funding the cost.
For a portfolio, WEC sits where Constellation and Vistra did two years ago, before the market priced in nuclear’s renaissance. The regulated structure limits upside surprises but also limits catastrophic drawdowns. A position sized for a multi-year hold, not a trade, captures the rate base expansion and dividend compounding without betting on a single regulatory outcome.
The Takeaway
The most durable wealth-building insight from this week is simple: the AI electricity boom does not belong only to merchant generators like Constellation or Vistra. It is flowing, deal by deal, into the rate bases of regulated utilities. WEC Energy is the clearest example of that shift in motion right now, and the market has not fully priced it.