The CIA Accidentally Discovered the Rare Earth MOTHERLODE
…And One $5 Stock Sits at the Center of it ALL
Dear Reader,
Inside the CIA’s private museum at Langley sits a strange black rock, sealed in a block of clear plastic.
It looks like a lump of coal… but it’s NOT.
It’s a tiny piece of the biggest discovery of critical resources ever made… a $16 trillion treasure trove that 60 Minutes calls “staggering.”
And one small company you can buy today for about $5 holds the rights to harvest the richest stretch.
Click here for the jaw-dropping TRUE story.
As you’ll see…
The CIA stumbled onto it during one of the boldest secret missions of the Cold War.
To hide what they were really doing, they teamed up with billionaire Howard Hughes and invented a fake mining company.
The whole world bought the story.
But when the mission was over, the CIA came back with something nobody expected… rocks as heavy as gold bricks, packed with rare earths, cobalt, nickel and lithium.
These are the same materials that are driving the 21st-century economy.
America can’t build a fighter jet, an electric car or an AI data center without them.
A $16 Trillion Chess Move that practically nobody sees coming…
At the center of it all is the only company with the technology and track record to harvest this rare earth motherlode.
A publicly traded stock you can buy right now for $5.
The last time Trump backed a mining company like this, its stock shot up 407% in a single week. This time, I believe this stock could hit $50 by the time Trump’s second term is over.
Click here for the details before Trump makes his move.
Regards,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. A former CIA insider just sent me Trump’s executive order by OVERNIGHT FedEx, with one section highlighted in yellow. Click here to see why it could be the key to 1,000% gains before Trump leaves the White House.
Shopify Beat on Margins. The Market Punished It Anyway.
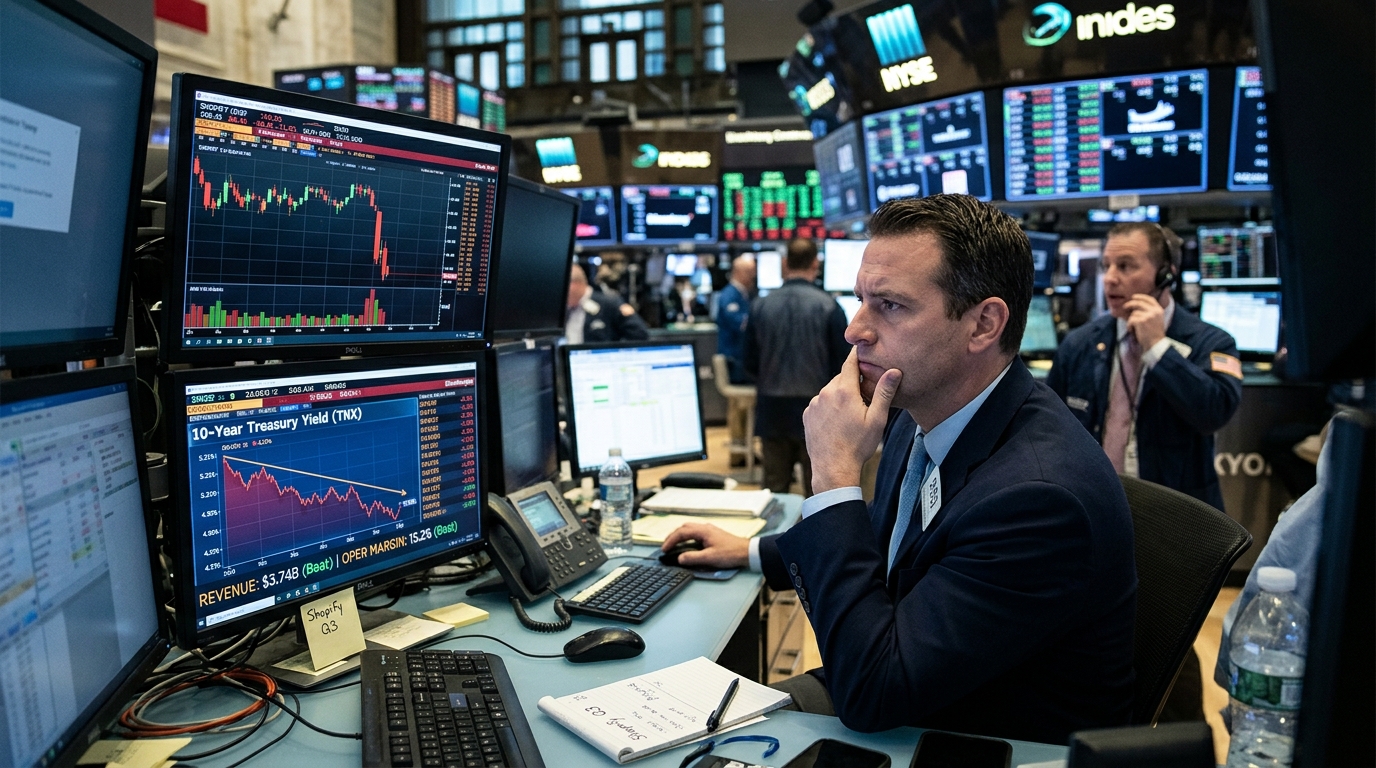
There is a tension worth naming directly. Shopify reported Q3 results this morning, posting 32% revenue growth and a 22% free cash flow margin. Those are not distress numbers. Yet shares fell sharply, even as revenue came in at $3.742 billion, essentially in line with Wall Street’s consensus, and an operating margin of 15.2% improved from roughly 12.1% a year earlier.
The selloff is not irrational. It is a valuation argument wearing an earnings costume.
Over the past month, the 10-year Treasury yield has fallen from an early-October peak near 5.31% to about 4.93% recently. That matters for Shopify specifically because the 10-year is the risk-free rate in most valuation work: raise it, and the present value of distant cash flows falls, which is why long-duration growth stocks sell off hardest when yields spike. Shopify is exactly that kind of business. Its earnings power is weighted toward years five through ten, not the next two quarters.
For equity investors, the relevance is sharpest in long-duration assets: growth stocks, utilities, and other rate-sensitive sectors whose valuations are most exposed to discounting at higher rates. Shopify sits at the front of that line. When the 10-year ran from roughly the mid-4% range earlier this year toward that 5.31% peak in early October, the multiple compression was mechanical. Even at about 4.93%, the yield is still meaningfully above where it was 12 months ago. Markets are still recalibrating what a Shopify cash flow stream is worth at this rate level.
The yield pressure on long-duration equities is not isolated to Shopify. A 10-year Treasury climbing past 5% has forced broad rotation out of high-multiple growth stocks across the market.
Dig into the actual business and the structural case holds. Free cash flow margin improved 150 basis points from expense leverage, B2B GMV grew 74%, offline GMV rose 30%, and Shop Pay GMV expanded over 50% year over year. The gross margin compression, from 52.6% in Q3 2023 to 47.6% today, reflects the deliberate shift toward merchant solutions revenue, which carries lower margins but scales directly with GMV growth. That is a mix problem, not a deterioration problem.
For the third consecutive quarter, year-over-year and sequential margin improvements were driven by expansion in Shopify Payments from savings negotiated with partners across the full payments ecosystem. That is operating leverage with a durable source. It is not a one-time line item.
Where the bear case has real weight is on starting valuation. The draft cited an ~85x forward earnings multiple, but commonly cited forward P/E estimates around this release were lower than that, and the exact figure depends heavily on which consensus window and earnings definition you use. With major forecasters still penciling in a 10-year yield around the 5% neighborhood into late 2026, the rate environment is not about to become dramatically easier for high-multiple growth. Modest yield relief helps at the margin; it does not reset the multiple math.
The honest framing is this: Shopify’s business performed well. Its stock is being priced for a world where the risk-free rate is structurally higher than investors assumed two years ago. Those are two separate conversations, and conflating them is what today’s selloff is doing. For investors with a five-year horizon and the discipline to hold through rate-driven volatility, the gap between business quality and stock price action may be the opportunity. But it requires accepting that the 10-year, not the earnings release, is setting the price right now.