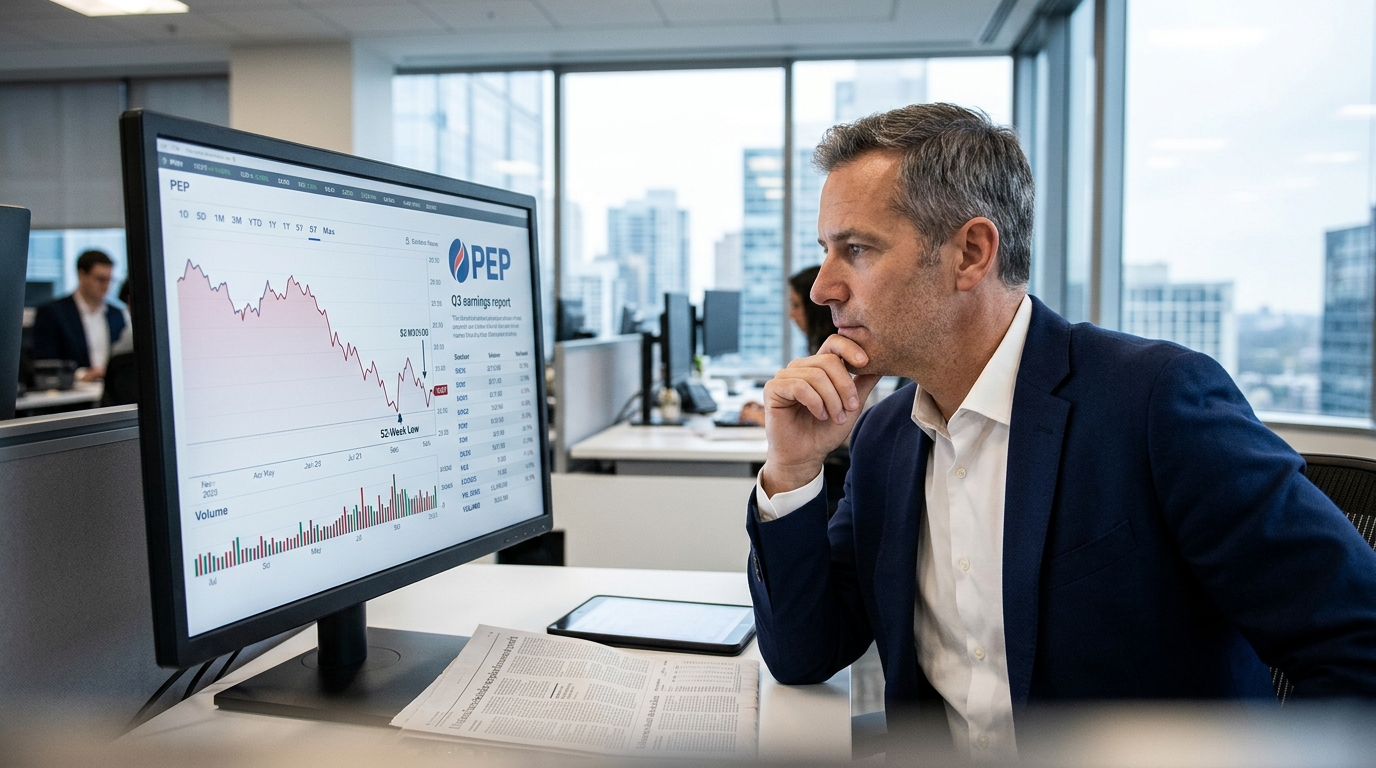
PepsiCo closed at $126.72 on September 30, undercutting its prior 52-week low of $128.15 set on September 24 by 1.11%. The company has now taken out two consecutive floors in less than a week. Q3 results arrive October 8. That report either rebuilds the case or accelerates the selling.
PEP is down roughly 26% from its February high of $171.48. The dividend yield has risen to approximately 4.7% as a mechanical result of the price decline. The forward price-to-earnings ratio has compressed to roughly 15x, down from over 26x at the end of 2021.
The Business
PepsiCo operates two distinct businesses: a global convenient foods portfolio anchored by Frito-Lay, and a beverage operation competing directly with Coca-Cola. The company generated nearly $94 billion in net revenue in 2025. The snack business carries structurally higher margins, which is why every volume data point from Frito-Lay North America carries disproportionate weight in the model.
The 2026 bull case rested on a North America Foods volume recovery. Q1 delivered it: PFNA volume grew 2%, adding 300 million consumption occasions versus the prior year.
Why Wall Street Is Paying Attention
Q2 reversed that momentum domestically. North American food volume came in flat. North American beverages dropped 4%. CFO Steve Schmitt said the company now expects North America to gradually improve at a more moderate pace than management thought coming into Q2.
The international business offers a counterweight. Global convenient foods organic volume grew 3% in Q2 and Asia Pacific Foods volume jumped 10%. The weakness is concentrated in North America, where margins are highest, which is exactly why it matters.
What Is Driving the Opportunity
October 8 answers one question: did North American volumes stabilize through the summer? The U.S. salty-snack category has been one of the few areas in U.S. food still growing volume, and PepsiCo said PFNA gained volume market share in Q2. Analysts model Q3 EBITDA near $5.35 billion, implying roughly 8% growth year over year. PepsiCo produces more quarterly EBITDA than either Coca-Cola or Keurig Dr Pepper across every forward period analysts currently model. At $126, none of that trajectory is priced in.
What Could Go Wrong
GLP-1 weight-loss drugs add structural demand destruction for snacks that no shelf reset addresses. The magnitude is not quantifiable, and the market is pricing in genuine uncertainty rather than a specific number.
North American beverages falling 4% in Q2 is harder to explain away. Coca-Cola grew global unit case volume through the same period. A second consecutive quarter of deteriorating North American beverage volume would broaden the concern from a snack recovery into a broader portfolio question.
The Bottom Line
PepsiCo at $126 trades at a multi-year low for a business generating over $8 per share in annual earnings and paying a $5.92 annualized dividend. October 8 is not about whether PepsiCo is a sound business over the next five years. It is about whether Q3 volume data confirms that Q2’s North American setback was a pause rather than a reversal. If management defends full-year guidance and PFNA volume returns to growth, the technical breakdown becomes an entry point. If volumes miss again, there is no floor from the past year’s range to establish support.